MARSEILLE : Commenting on the full-year 2022 results, Rodolphe Saadé, Chairman and Chief Executive Officer of the CMA CGM Group, said: “Our Group achieved exceptional, historic results in 2022 that have enabled us to invest significantly in operations across our business, step up our energy transition and share the created value with our employees.
As trade returns to normal and freight rates decline, our strategy and recent investments will prove all the more relevant and allow us to look forward to 2023 with confidence.
Leveraging our financial strength and entrepreneurial spirit, we will continue to develop our operations in transport and logistics to meet the needs of our customers, who expect a group like ours to deliver the best service at the lowest possible cost, with the smallest environmental footprint.”
2022 Highlights
A HISTORIC PERFORMANCE DRIVEN BY EXCEPTIONAL CIRCUMSTANCES
With the start of 2022 already impacted by post-Covid 19 congestions, major geopolitical tensions, most notably the Russian-Ukrainian conflict, then drove a sharp spike in energy costs, which in turn led to widespread inflationary pressures. These factors triggered a slowdown in freight demand, helping to gradually ease port terminal congestions, especially in the fourth quarter. To this end, the Group reinvested almost 90% of its 2022 net profits in its industrial assets and capabilities, while also strengthening its balance sheet and enhancing its financial flexibility.
Shipping : an exceptional year despite a slowdown in global trade in the final quarter
For the maritime shipping industry, 2022 was a year of contrasting halves. Behind the relative stability in full-year volumes transported by the Group (down 1.3% YoY) lay major disparities between the first and second halves, as well as among the main shipping routes.
• In the first half, while demand for consumer goods remained strong, shipping capacity was constrained by port congestions and other disruptions impacting local supply chains around the world.
• The second half saw a demand shock accentuated in the fourth quarter by a wave of inventory destocking in the U.S. and the impact of persistent inflation on consumer spending. In addition, the situation was exacerbated by the energy crisis in Europe. As a result, volumes transported by the Group on East-West routes declined by 7.2% in the fourth quarter, while the North-South routes proved more resilient thanks in particular to the sustained growth of certain emerging economies. Lastly, intra-regional volumes suffered both from the Russian-Ukrainian conflict (with the termination of Russian services) and from the lack of capacity in Asia early in the year. The decline in demand spurred a quicker return to normal spot freight rates in the final quarter.
Investments in our terminal portfolio
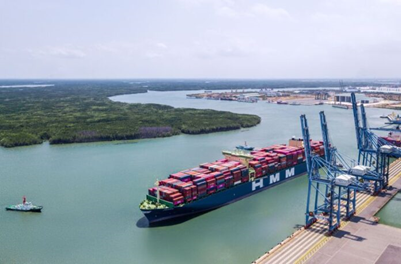
The Group owns equity stakes in more than 56 port terminals and projects around the world. In 2022, CMA CGM stepped up its investments in industry-leading infrastructure to continue supporting growth in its shipping lines and enhance the quality of its customer service.
The Group now owns 100% of the Fenix Marine Services (FMS) terminal in the Long Beach/Los Angeles port area, the US’s leading West Coast import gateway; has started its 10-year operation to manage, operate and maintain the Beirut container terminal; and has been awarded the concession for the Nhava Sheva terminal in India, with its partner JM Baxi.
Late in the year, CMA CGM announced the acquisition of two strategic terminals at the Port of New York, GCT Bayonne and GCT New York, which have a combined capacity of two million TEUs per year with potential for further expansion up to almost double the current capacity. The closing of this transaction remains subject to regulatory approvals.
Logistics: expanding CEVA's logistics capabilities with new acquisitions
In 2022, the CMA CGM Group continued developing an integrated suite of logistics solutions to support its customers’ supply chains. Following the acquisition of CEVA Logistics in 2019, CMA CGM accelerated its transformation in 2022 with the completion of three strategic acquisitions
Creation of a new special Shipping Department
In 2023, the Group will pursue its expansion into transport using roll-on/roll-off (ro-ro) ships and expand its offering in finished vehicle logistics, by capitalizing on the expertise of Gefco, now a part of our CEVA Logistics subsidiary.
ACTIVITIES & FINANCIAL PERFORMANCE IN 2022
Group: solid financial performance and lower debt
• Full-year 2022 revenue stood at USD 74.5 billion, a 33% increase versus 2021 led by the Group’s maritime shipping business.
• EBITDA came to USD 33.3 billion, representing an EBITDA margin of 44.7% or 3.4 points higher than the year before.
• Net income, Group share amounted to USD 24.9 billion for the year.
• The Group continued to strengthen its balance sheet, with net debt holding steady at USD 7.7 billion as of December 31, 2022. In addition, the Group has USD 11.6 billion in short-term financial assets.
Shipping: strong growth in revenue
In 2022, 21.7 million TEUs were transported, down 1.3% from 2021. Revenue from the maritime shipping operations rose by 30.1% year-on-year, to USD 58.9 billion.
EBITDA stood at USD 31.6 billion, versus USD 22.1 billion in 2021. EBITDA margin widened by five points to 53.7%, lifted by the USD 2,771 in average revenue per TEU during the year.
Logistics: improved financial performance
Revenue from the logistics business rose by a steep 47.6% to USD 16.1 billion versus 2021. Growth was supported by robust expansion in the freight management business, particularly in the first half, as well as by recent acquisitions.
EBITDA ended the year at USD 1,223 million, a 38.7% increase on 2021.
OUTLOOK
Geopolitical tensions, macroeconomic uncertainty, and sharp decrease of freight rates
Second-half 2022 trends remained at play in 2023, as market conditions in the transport and logistics industry continue to deteriorate. The balance between supply and demand is expected to remain challenging, as capacity is expected to increase – in both maritime shipping (easing of port congestion, delivery of new vessels) and air freight (return of passenger belly capacity). At the same time, demand prospects seem uncertain (dealer inventory destocking in the US, consumer purchasing power under pressure).
Nevertheless, certain macroeconomic signals are stabilizing. In the U.S., consumer spending and the labor market remain resilient despite the very aggressive tightening pursued by the Federal Reserve in recent months. In the European Union, recession has been avoided for the moment. Some emerging markets in Latin America and Southeast Asia remain strong.
The Group is closely monitoring the evolutions in the economic and geopolitical situation, despite limited visibility over the rest of the year, and remains confident in its ability to weather the cycle thanks to the diversification of its businesses and its financial strength.